
By Boutaïna Deixonne, Head of Euro Investment Grade and High-Yield Credit
- Despite significant challenges in 2026 the European investment-grade credit market has remained remarkably resilient
- While volatility is expected to persist, the outlook remains constructive, supported by positive economic growth and healthy corporate fundamentals
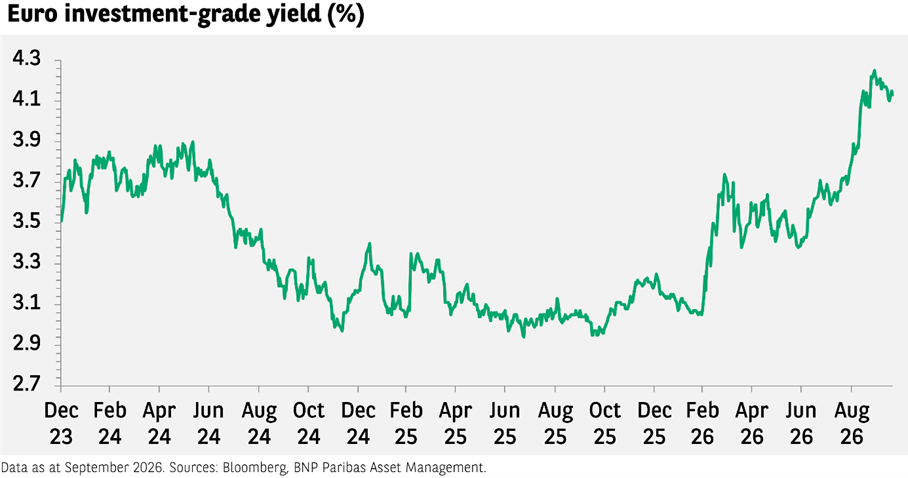
- We believe current all-in yield levels provide an attractive entry point for investors, helping to offset pressures from higher rates and supporting long-term demand
2026 has been marked by significant challenges – heightened interest-rate volatility, elevated energy prices, persistent inflation concerns and frequent shifts in monetary policy expectations.
These factors have largely overshadowed the risks that dominated discussions at the beginning of the year, particularly those related to the impact of artificial intelligence on corporate business models and concerns surrounding private credit markets.
Despite persistent geopolitical uncertainties, the European investment-grade credit market has demonstrated remarkable resilience. That said, market dispersion has increased since the summer, with cyclical sectors and high-yield spreads underperforming.
In Europe, the sharp rise in government bond yields pushed total returns into negative territory, weighing somewhat on investor flows. Nevertheless, investment-grade spreads have remained resilient and have outperformed other fixed-income segments, notably euro high yield.
New year expectations
Looking ahead to 2027, we expect volatility to remain elevated against a backdrop of fiscal concerns, increased sovereign funding needs, elections in several major economies and uncertainty surrounding future central banks’ actions.
Even so, we remain constructive on the credit asset class. Economic growth remains positive, corporate fundamentals are healthy, and all-in yields continue to offer an attractive entry point for investors. These factors should ultimately support demand for credit despite periodic bouts of volatility.
Investors generally raise three key concerns regarding the European credit outlook: namely the impact of higher rates on corporate fundamentals; the outlook for flows into the asset class; and the potential consequences of elevated primary market supply. In our view, each of these concerns is valid but ultimately overstated.
The yield factor
The first concern is whether the sharp increase in yields could eventually weaken corporate balance sheets and lead to rating pressure. While this risk is more relevant for highly leveraged issuers in the high-yield universe, European investment-grade corporates enter this period of higher rates from a position of strength.
Although some sectors and issuers face structural and cyclical challenges and rising funding costs, the broader picture remains favourable. Cash-flow generation is solid, profitability remains healthy and leverage is generally contained.
Recent earnings seasons have confirmed these trends, with revenue growth remaining resilient and credit metrics continuing to improve. Robust earnings should continue to offset part of the pressure from a prolonged period of elevated rates.
Consequently, we expect investment-grade fundamentals to remain broadly stable. However, we remain more selective in the lower-rated high-yield segment, where refinancing needs are more front-loaded and financial flexibility is more limited.
Policy influence
The second question is related to the impact of a higher interest rate environment on demand for credit. Historically, negative total returns have tended to weigh on investor flows, and the recent increase in rate volatility has indeed triggered periods of outflows from credit markets.
However, these outflows have remained relatively modest compared with previous market stress episodes. We believe this resilience is largely explained by the significantly higher income available in fixed income today.
Current yield levels are increasingly attractive for a broad range of investors, including pension funds, insurance companies and fixed-to-maturity products.
While we believe the structural backdrop for flows remains supportive, a sustained recovery in inflows will likely require greater stability in both underlying rates and rate volatility.
Once this adjustment phase is complete, the combination of attractive income and solid fundamentals should encourage investors to increase allocations to the asset class.
Issuance issues
The final concern is supply absorption, particularly financing needs from hyperscalers and AI-related investments. This has been one of the most frequently cited risks among investment-grade investors over the past 12 months.
While issuance has been particularly dynamic in the US market, totalling approximately $180 billion, it has so far been much more moderate in Europe, with only around €25 billion year-to-date.1
Although additional issuance remains possible before year-end, market volatility could encourage issuers to adopt a more measured approach in the near term. For 2027, issuance from hyperscalers could accelerate further.
Nevertheless, we believe that if issuance is spread over different maturities and if it becomes more programmatic over time, this could allow investors to better anticipate funding needs as long as issuers continue to show strong earnings and business models.
Opportunities ahead
Overall, we remain constructive on European credit, supported by strong corporate fundamentals, resilient economic activity and attractive all-in yield levels. While volatility is likely to remain elevated and spread dispersion may increase further, these conditions should also create opportunities for active investors to generate alpha.
We continue to see attractive opportunities across selected areas of the market, including higher-quality, high-yield, subordinated financial debt and parts of the real estate sector.
In an environment characterised by greater differentiation between issuers, security selection will become increasingly important to capture the opportunities ahead.
[1] Source: Bloomberg, as at 30 October 2026.


